What Is ROI in Marketing?
Marketing ROI is the profit you get back from marketing relative to what you spent, calculated as (attributed profit minus total acquisition spend) ÷ total acquisition spend for a fixed time window.
Here’s what matters most if you need a CFO-safe number today:
- Use one fixed attribution window and match revenue and spend to the exact same dates.
- Count net new customers only, excluding renewals, reactivations, and returning buyers.
- Include total acquisition spend: media plus agency fees, creator costs, and contractor time.
- Keep ROAS separate; it can look strong while payback period is dangerously slow.
- Set decision rules upfront: pause when ROI misses targets, not after rationalizing results.
- Improve ROI fastest with controlled creative testing: change one variable per batch.
We built Advertisable AI Studio for the exact moment you are in: you need measurable iteration, not more dashboards. Our URL-to-ad workflow uses Brand DNA guardrails, storyboard approval, and scene-level edits so you can generate variants, run one-variable batches, and get 48 to 72 hour readouts that tie creative changes back to CAC, payback period, and marketing ROI.
Before you optimize anything, you need a shared definition of what “return” actually means in marketing, because ROI is profit returned for each dollar spent, not a platform number in isolation.
Marketing ROI means profit returned for each dollar spent
In marketing, “return” only matters if it is profit, not revenue. ROI expresses that profit return as a percentage of what you spent, scoped to a specific campaign or a defined reporting period (for example, a month or a campaign flight).
The plain ROI formula
ROI is a profit percentage: it tells you how much profit you made for each dollar you spent. If ROI is 0%, you broke even. If ROI is 100%, you doubled your money in profit terms.
The math is straightforward and should be consistent every time you report it: ROI = (return - cost) / cost, then multiply by 100 to convert it into a percentage. Harvard Business School frames ROI the same way: net profit divided by investment cost, expressed as a percent.
The operator check we use: your “return” input must already be profit, not top-line revenue. Otherwise you are calculating a ratio that can look healthy while still failing profitability.
- ROI = (return
- cost) / cost
- ROI (%) = [(return - cost) / cost] x 100
A worked ROI percentage example
Assume you spent $1,000 on marketing and you can attribute $3,000 in profit to that same campaign or period. Your ROI is 200%.
Calculation: ROI = ($3,000 - $1,000) / $1,000 = $2,000 / $1,000 = 2. Multiply by 100 and you get 200%.
Interpretation: a 200% ROI means you earned back your original $1,000 plus an additional $2,000 in profit. The only requirement for this number to be decision-grade is that the $1,000 cost and the $3,000 profit are measured over the same fixed campaign or time window.
- Cost = $1,000
- Return (profit) = $3,000
- ROI (%) = [($3,000 - $1,000) / $1,000] x 100 = 200%
Why teams report strong ROAS and still lose money
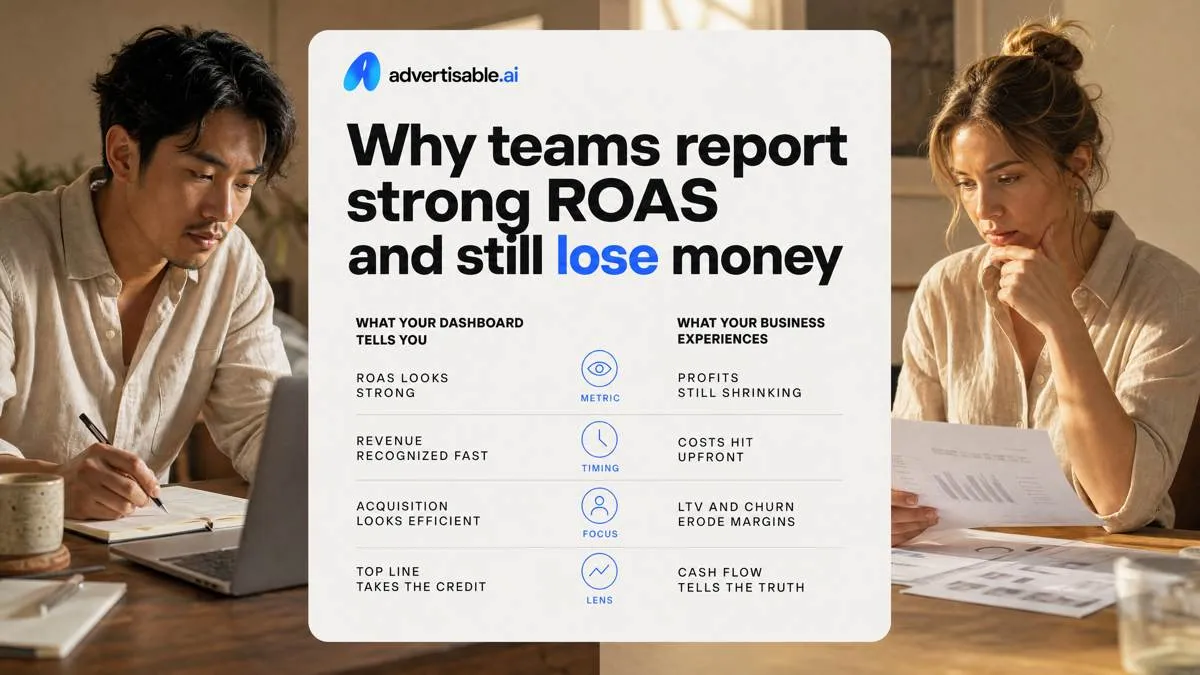
This failure mode is common: your dashboard shows strong ROAS, but your bank balance and P&L say otherwise. The gap happens because ROAS is a revenue lens, while ROI is a profit and cash lens, and those diverge fast when costs and timing move.
If you need the ROAS definition first, see What Is Return on Ad Spend (ROAS)?. Then sanity-check the rest of the unit economics around it: CAC (what you paid to acquire a net new customer), LTV (what that customer returns over time), and conversion rate (how efficiently clicks become purchases).
ROI is profit and whole picture
ROI answers the only question finance ultimately cares about: did this investment pay off in profit, not just revenue. If you spent $10,000 to generate $12,000 in sales, ROI can still be negative once your costs are counted.
For acquisition, ROI has to include all costs required to produce and run the customer acquisition engine, not just platform spend. It also has to reflect gross margin reality, because profit is earned after COGS, not at the top line.
- Include all acquisition costs: media, agency fees, creator costs, and contractor time treated as acquisition ops
- Apply gross margin to the revenue you are crediting to ads before calling it “return”
- Use one consistent time window for both spend and profit so you are not comparing this week’s spend to next month’s revenue
ROAS is revenue per ad dollar
ROAS is revenue attributed to ads divided by ad spend. It is an ad-specific efficiency metric, which makes it useful for creative and bidding decisions, but dangerous as a stand-in for profitability.
By design, ROAS ignores COGS and most overhead. In practice, teams also compute it on media-spend only, which can make performance look “clean” while real acquisition costs are rising in the background.
This is why marketing measurement experts draw a hard line between “ads generate sales” and “the business makes money on those sales.”
- ROAS numerator: attributed revenue (not profit)
- ROAS denominator: usually platform media spend only
- Excluded: product costs, shipping, payment fees, support, refunds, and most operating overhead
When ROAS rises but ROI falls
ROAS can improve while ROI declines because you are getting more revenue per ad dollar, but keeping less of that revenue, or waiting longer to collect it. We see this most often when promotions, operational costs, or payback timing shift.
Treat this as an alignment bug: your ad metric is improving, but your unit economics or cash cycle is deteriorating.
- Thin margins or discounts: higher conversion from promos can lift ROAS while contribution margin collapses
- Rising fulfilment and refunds: shipping, returns, and chargebacks increase post-purchase costs ROAS never sees
- Slow cash payback timing: a customer might repay CAC over months, not within the reporting window, creating a cash crunch even with “good” ROAS
A CFO-safe ROI audit: lock numerator, denominator, and window
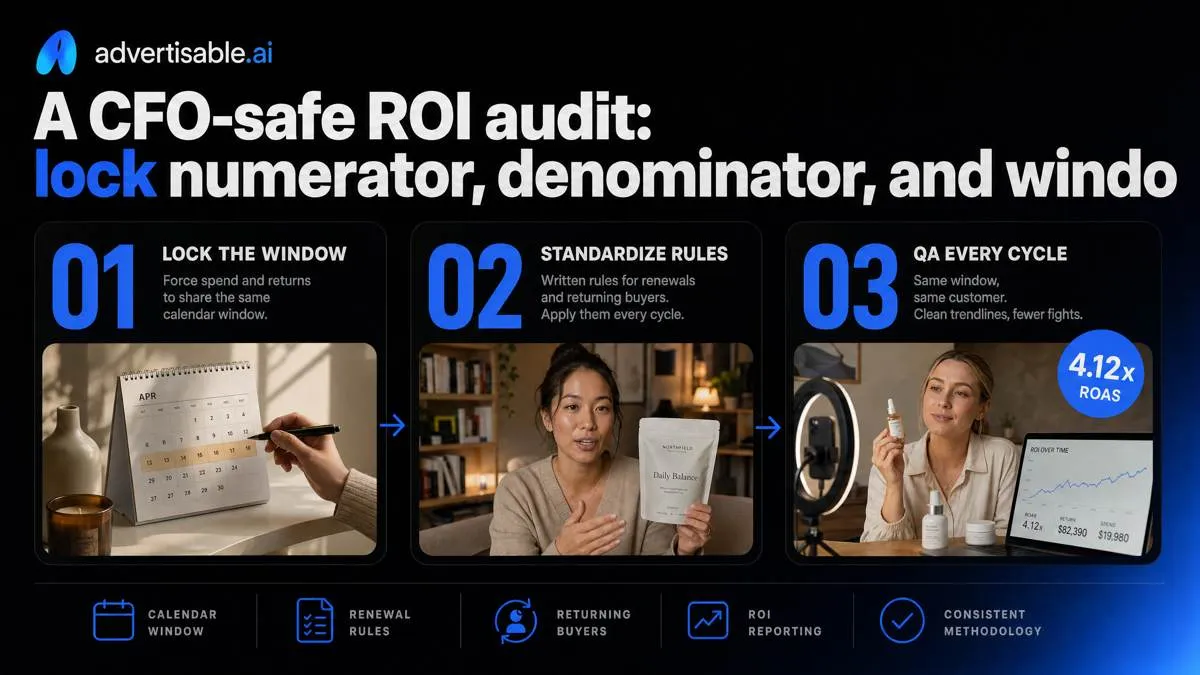
Most ROI disputes are bookkeeping disputes: the “return” lands in one month, the spend is reported in another, and your denominator silently changes. CFO-safe reporting starts by forcing spend and returns to share the same calendar window before you do any division.
You also need written rules for renewals and returning buyers. If renewals are counted as “return” in one month but excluded or included differently the next, your trendline is noise.
QA this every cycle: same window, same customer inclusion rules, same cost categories. If any of those change, you are not comparing performance, you are comparing definitions.
Lock the numerator: return definition
Lock “return” as profit, not top-line revenue. Finance will not sign off on a numerator that ignores fulfillment, COGS, refunds, or payment processing, because it can show “up and to the right” while cash gets tighter.
Write down whether you are using gross profit (revenue minus COGS) or contribution margin (gross profit minus variable costs like shipping, payment fees, and support burden). The key is not which you choose, it is that you pick one and keep it constant month to month.
Separate acquisition return from retention return. Acquisition ROI should be tied to net new customers and their profit, while retention ROI belongs in a separate bucket so you do not “save” acquisition performance with revenue you would have gotten anyway.
- Acceptance criterion: your numerator is a profit measure, not revenue, and includes refunds/chargebacks in the same window.
- Decision rule: choose gross profit or contribution margin once, document the components, and do not swap mid-quarter.
- Segmentation rule: report acquisition return for first-ever purchases only; report renewals and repeat purchases in a retention line item with its own definition.
Lock the denominator: marketing cost
Your denominator must be total acquisition cost, not “media spend.” Teams drift here by excluding real costs in bad months and re-including them in good months, then calling the change “performance.”
Include media plus platform fees, then layer in the costs required to ship and manage the work: creative production and tools, and agency and contractor labour. If you are using a tool primarily to produce paid acquisition creative, it belongs in the acquisition cost pool for this metric.
- Media plus platform fees: ad spend, platform billing fees, and any required tracking or serving fees tied directly to paid acquisition.
- Creative production and tools: creator invoices, editing resources, and production tools used to generate paid assets; if you produce high-volume variations in Advertisable AI Studio for paid social, classify that as acquisition ops cost for the same period.
- Agency and contractor labour: retained fees, project-based work, and fractional operators whose hours are dedicated to acquisition.
Lock the time window and payback
Match spend dates and return dates or your ROI is mechanically wrong. The fastest way to create month-to-month “improvement” without changing reality is to book spend this month and let revenue roll in next month, then claim the ratio got better.
Choose one attribution window and stick to it. For creative testing, we typically read early signal in 48-72 hours, but your ROI reporting window still needs a consistent rule so you are not extending the window to rescue weak performance.
Pair ROI with payback period, because profitable-on-paper can still be cash-unsafe. Two programs can show the same profit return but have radically different time-to-recover-CAC, which changes how aggressively you can scale.
- Date matching QA: spend and attributed profit must be pulled for the exact same start and end timestamps.
- Attribution window rule: pick a single window (for example, fixed 48-72 hour readouts for tests, and a fixed weekly or monthly window for reporting) and do not change it without restating historicals.
- Payback pairing: report ROI and payback period side by side for every acquisition cohort so finance can see both efficiency and cash timing.
Why marketing ROI is harder than it looks in real data
A clean ROI number is a comfort blanket, but real acquisition data is messy. Your job is not to “find the perfect ROI”, it is to declare the assumptions you control, then apply them the same way every time so the metric stays comparable month to month.
Attribution is not the return
Attribution tells you where a conversion was credited, not what your spend truly caused. That gap matters because incrementality asks a different question: what profit would not have happened without this spend, even if another channel would have “won” credit.
Multi-touch journeys make this worse. A customer might see a YouTube ad, click a Meta ad two days later, then buy after a branded search or an offline conversation. Most reporting collapses that into one winner, even though the conversion was produced by a sequence.
Overlap creates halo and double counting. When you run multiple channels at once, you often lift conversion rate across the whole account, but platform dashboards still claim the full conversion value inside their own walls. The result is two “profitable” channel reports that cannot both be true in the same P and L.
- Acceptance criterion: your ROI numerator is explicitly labeled as “attributed profit” unless you have an incrementality method behind it
- QA check: compare total attributed conversions across platforms vs. total net new customers in your system of record; if the sum exceeds reality, overlap is inflating channel views
Time lag breaks naive ROI
Spend happens today; revenue often lands later. attribution timing research describes conversion lag ranging from minutes to days or weeks, which means same-day or same-week ROI can be directionally wrong even when tracking is “working.”
Blended averages hide the lag. A blended ROI number mixes brand new cohorts (not yet paid back) with older cohorts (already repeating), so it can look stable while your current acquisition economics are deteriorating.
Declare the return window up front. If you report ROI on a 7-day, 30-day, or 90-day window, lock it and time-match spend and profit inside that same window so you are not comparing this week’s costs to next month’s revenue.
- Cohort rule: evaluate each acquisition cohort on the same day count since first purchase
- Reporting rule: the window stated in the header must match the dates used in both numerator and denominator
Consistency beats false precision
Decision-grade measurement comes from consistency, not extra decimals. We have seen teams lose credibility by tweaking definitions mid-report to “explain” a change; finance remembers the inconsistency, not the spreadsheet.
Lock your inputs in writing and keep the same model month to month. Change the creative, targeting, or budget, but hold the measurement contract constant so movement in the metric reflects reality, not reporting drift.
- Write the numerator: what costs are included in total acquisition spend, and which are excluded
- Write the denominator: net new customers only (first-ever purchase), with the exact data source
- Write the time window: attribution window and return window, with start and end timestamps
- Report confidence: “high / medium / low” with the single biggest known limitation (for example, cross-channel overlap or missing offline touchpoints)
Common marketing ROI mistakes that quietly invalidate reports
Most bad ROI reports fail quietly, not loudly. Three culprits show up repeatedly: you overfit attribution until the number “looks right,” you exclude non-media costs that are required to acquire customers, and you set benchmark targets you cannot defend. Lock your method first, then let results be what they are.
Confusing ROI with ROAS
ROAS is revenue divided by media spend. ROI is profit divided by total acquisition spend, and that profit can be negative even when ROAS looks strong. The mismatch is revenue versus profit, and media-only cost versus the full investment.
The operational failure is margin blindness. A 3.0 ROAS can still be a cash loser when your gross margin is 40% and you are paying creators, agencies, and contractors on top of platform media. You do not need a complicated model to catch this, you just need the correct numerator and denominator.
When you present ROAS as ROI, executives draw the wrong conclusion: “scale spend” instead of “fix unit economics or creative.” That turns into budget whiplash when the P and L does not match the dashboard.
- QA check: confirm your “return” is attributed profit, not revenue
- QA check: confirm “investment” includes platform media plus agency fees, creator costs, and acquisition ops time
- Decision rule: do not approve scaling based on ROAS alone unless margin and non-media costs are explicitly in the same worksheet
Counting the wrong customers
Your denominator must be net new customers only, or your efficiency math is not comparable month to month. When renewals, returning buyers, or reactivations slip in, CAC looks lower without any real acquisition improvement.
This shows up most often when teams pull “customers” from a platform report and it includes existing buyers, or when CRM logic is not “first-ever purchase.” It also happens when organic customers get blended into paid counts, which dilutes acquisition performance and hides when paid is weakening.
- Include: first-time purchasers acquired in the same fixed reporting window as spend
- Exclude: renewals, reactivations, returning buyers, and any account that purchased before the window
- Avoid: blended organic counts inside a paid acquisition denominator
Judging too early for payback
You can calculate an early ROI, but you cannot pretend it is final when your product has a longer conversion or repurchase cycle. For many teams, 48-72 hour readouts are for direction on creative and offer quality, not for declaring profitability.
In practice, we treat early windows as a control loop: keep targeting and budget stable, test a single creative variable, and use the short window to decide what to regenerate next. Then you evaluate ROI on a longer, decision-grade window that matches how revenue actually lands.
Report payback period beside ROI. ROAS and even ROI can look acceptable while cash is tied up, and payback tells you how long it takes to recover acquisition spend.
- Early readout (48-72 hours): use to choose the next creative iteration, not to approve scaling
- Decision-grade review: use a fixed window aligned to your sales cycle and repurchase timing
- Reporting standard: show ROI and payback period on the same page so finance can sanity-check cash risk
Turn your locked ROI definition into a controlled creative test
Now that you have your numerator, denominator, and attribution window locked in writing, your job is to improve CAC and payback without breaking measurement. We do that by testing creative in single-variable batches, then reading results on a fixed 48 to 72 hour window.
In Advertisable AI Studio, generate 10 hook variants from your product URL while holding the storyboard body, proof element, and CTA constant. Approve the storyboard before you render. Acceptance criteria: Brand DNA guardrails match your offer, claims, and visuals, and each variation changes only the hook.
Launch the batch on Meta, TikTok, and YouTube. Set kill rules before you spend. After the readout, regenerate only the losing scenes, export platform-ready variations, and roll the next test.
Tie every iteration back to CAC, payback period, and the same ROI definition you just locked.
Frequently Asked Questions
### What's a good ROI for marketing?
A good ROI is the one that clears your cash constraints and payback requirement under the same numerator, denominator, and time window every month. If ROI looks positive but payback period is longer than your cash runway, you still have a scaling risk.
### What are ROI and KPI?
ROI is a financial outcome metric that tells you whether profit returned exceeded the total acquisition spend within a fixed window. KPIs are the operating metrics you use to control the system day to day, and they only matter if they map back to CAC, payback period, and your locked ROI definition.
### What is the difference between CAC and CPA?
CAC is total acquisition spend divided by net new customers, using a matched time window. CPA is cost per action and can count non-buyers, which makes it a weak input for unit economics and scaling decisions.
### Why does my ROAS look good but I am running out of cash?
ROAS ignores non-media acquisition costs and timing, so it can look healthy while payback period is slow. Put payback period next to ROAS and CAC, and do not change your attribution window mid-report to explain the gap.
### How do I know if creative fatigue is the problem or if my audience is exhausted?
Check sequence of decay: hook rate first, then hold rate, then CTR, then CVR. Creative fatigue usually shows as early drop in hook or hold rate on specific ads, while audience exhaustion shows as broad decline across most creatives with similar delivery.